




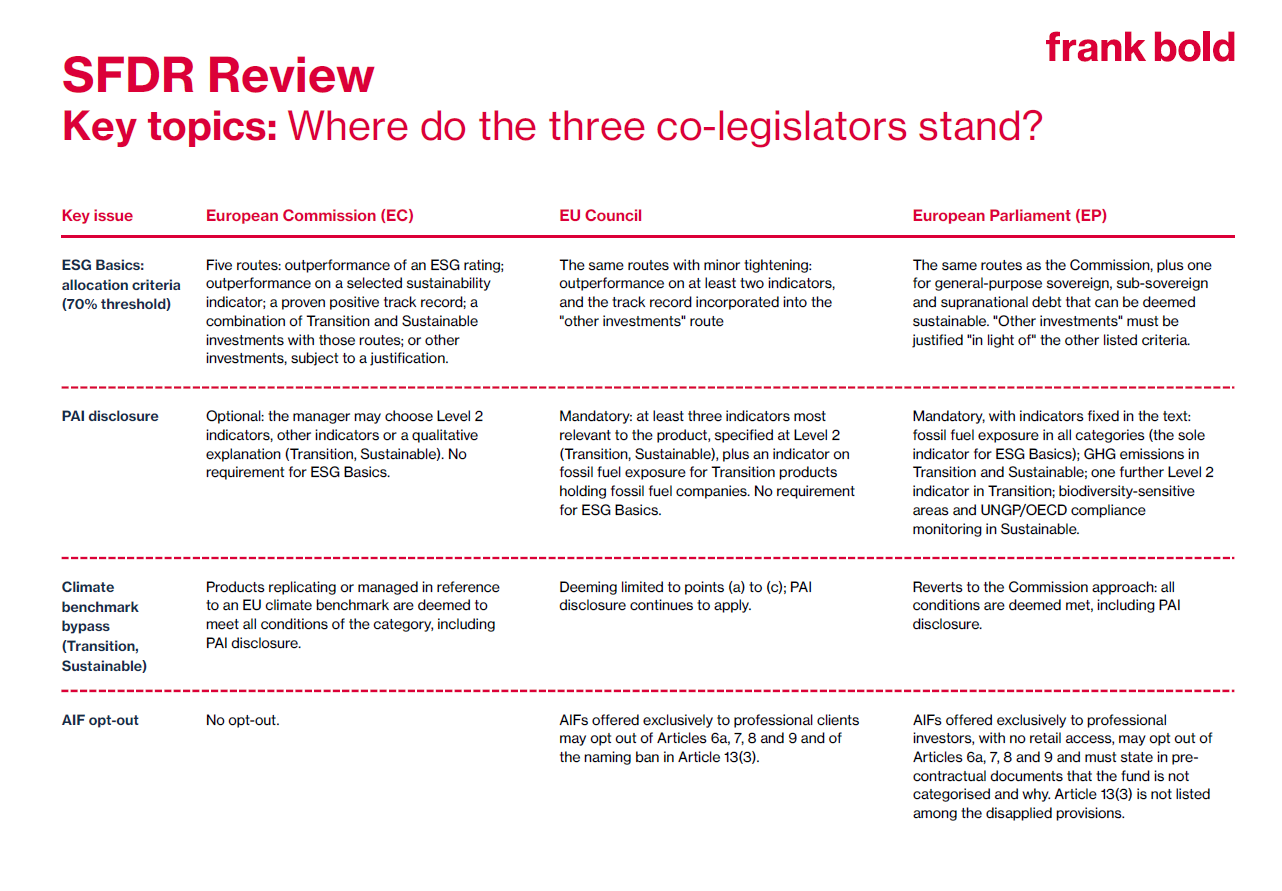
We've compared the different positions of the European Commission, Council of the EU and the European Parliament on the review of the SFDR. Read below our recommendations for this trilogue.
Trilogue negotiations on the SFDR review are due to start on 22 October and envisioned to finish by the end of 2026.
Parliament's text is the strongest of the three on most issues. Its main weakness is ESG Basics: retail investors receive a single indicator on fossil fuel exposure and little other information from which to assess performance, which risks perpetuating the catch-all character of Article 8 under SFDR 1.0.
Below, we set out our three priorities for the trilogue and the specific solutions we recommend to address them.
Parliament requires a single indicator for ESG Basics, exposure to the fossil fuel sector, and this must be retained. We ask that Parliament's own Transition wording be applied to Article 8, so that ESG Basics products report GHG emissions and fossil fuel exposure, together with one further indicator selected for relevance. This corresponds to the three indicators required by Council for Transition and Sustainable.
Council limits the effect of safe harbour to points (a) to (c) of the first subparagraph, so that PAI disclosure under point (d) continues to apply to products using the bypass. Parliament deems all conditions met. We ask the co-legislators to support the Council's scope.
The Commission proposal contains no opt-out, and we ask the co-legislators to maintain this position. If an opt-out is retained, Parliament's version is preferable to Council's, because it requires that no retail investor has access to the fund and requires a pre-contractual statement of non-categorisation.

The Committee on Legal Affairs of the European Parliament adopts improvements on the Corporate Sustainability Due Diligence Directive.
Amid current discussions on the shape of the European Sustainability Reporting Standards (ESRS), Frank Bold has developed an FAQ to answer the most important questions around the ESRS.
The European Parliament has adopted the Corporate Sustainability Reporting Directive (CSRD), which clarifies transparency obligations for large companies operating in the EU on their sustainability impacts, risks, and opportunities. Pursuant to the CSRD, companies across all sectors will report against the European Sustainability Reporting Standards, which were developed by the European Financial Reporting Advisory Group (EFRAG), submitted to the European Commission and published on 22 November.


